The Maurice Kilbride Cheadle Market Intelligence Report - October 26
The Confidence Gap
The autumn market is underway, but buyers are behaving differently.
House prices remain broadly stable and there is still genuine demand, particularly across stronger regions such as the North West. But greater choice and higher borrowing costs are making buyers more selective.
This isn't a market without buyers. It's a market in which buyers are becoming harder to convince.
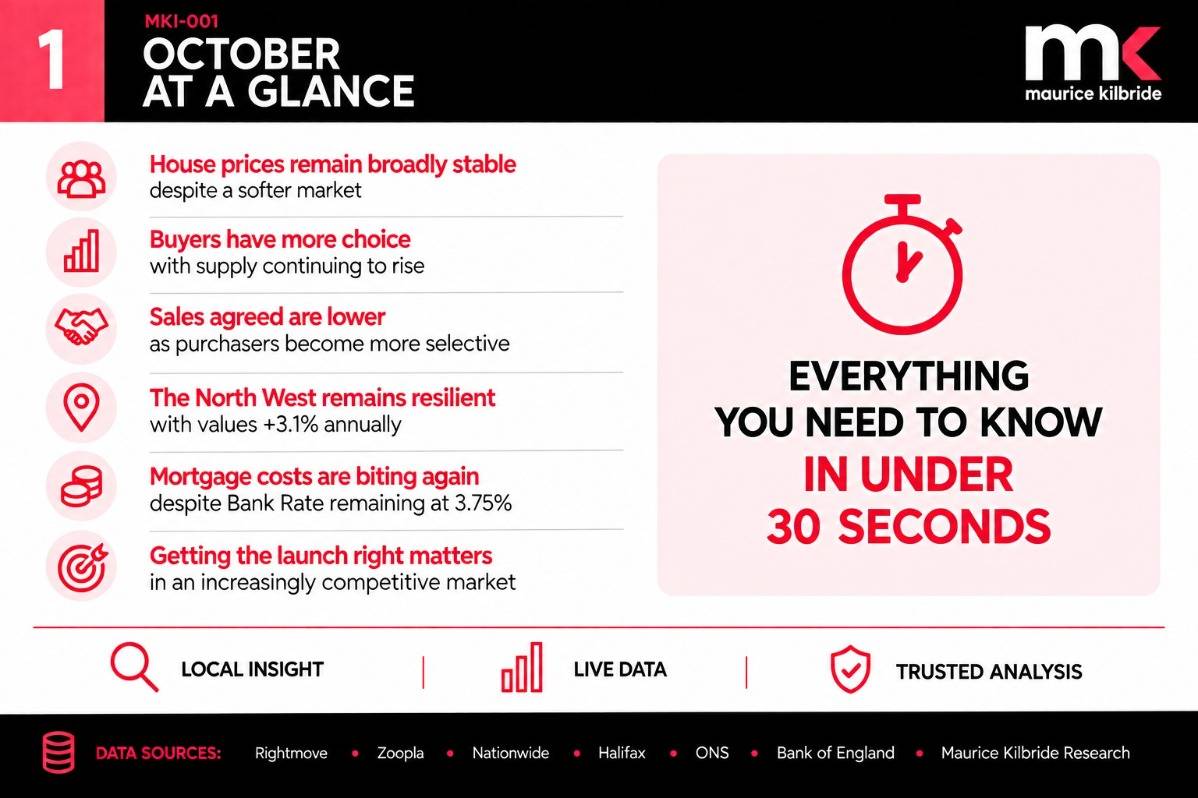
A more selective autumn market
The national picture remains resilient, but the balance has shifted.
Rightmove reports unusually high levels of available stock for this time of year, while Zoopla also points to increased choice for buyers.
For sellers, simply reaching the market is no longer enough. Standing out within it matters.
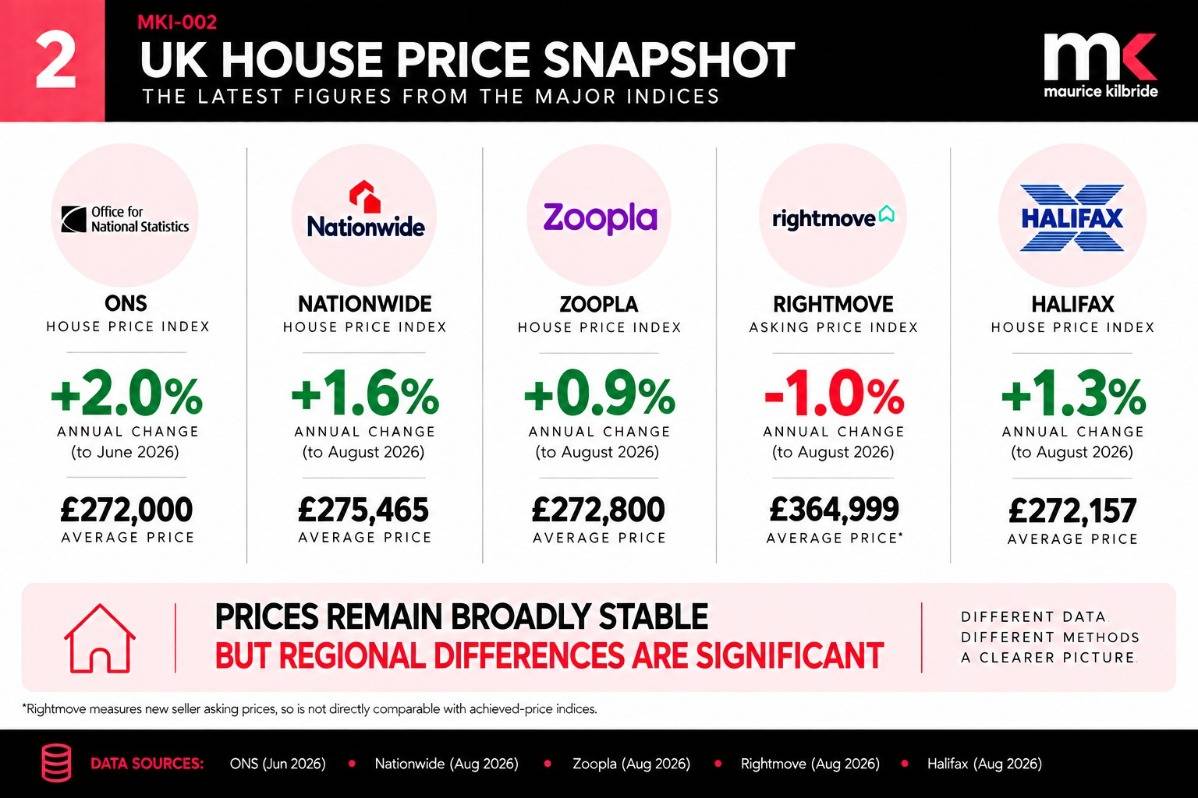
What are the major indices telling us?
No single house price index tells the whole story, which is why we look at them collectively.
Rightmove
September brought a modest recovery in new-seller asking prices, but buyer demand remains softer than a year ago. The message is one of stability rather than a dramatic autumn rebound.
Zoopla
Average values remain slightly higher annually, but the regional divide is significant. The North West continues to outperform the UK average, while parts of southern England remain weaker.
Nationwide, Halifax & ONS
These achieved-price measures provide a useful counterbalance to asking-price data. Collectively, they continue to point towards relatively modest national price movement rather than rapid growth.
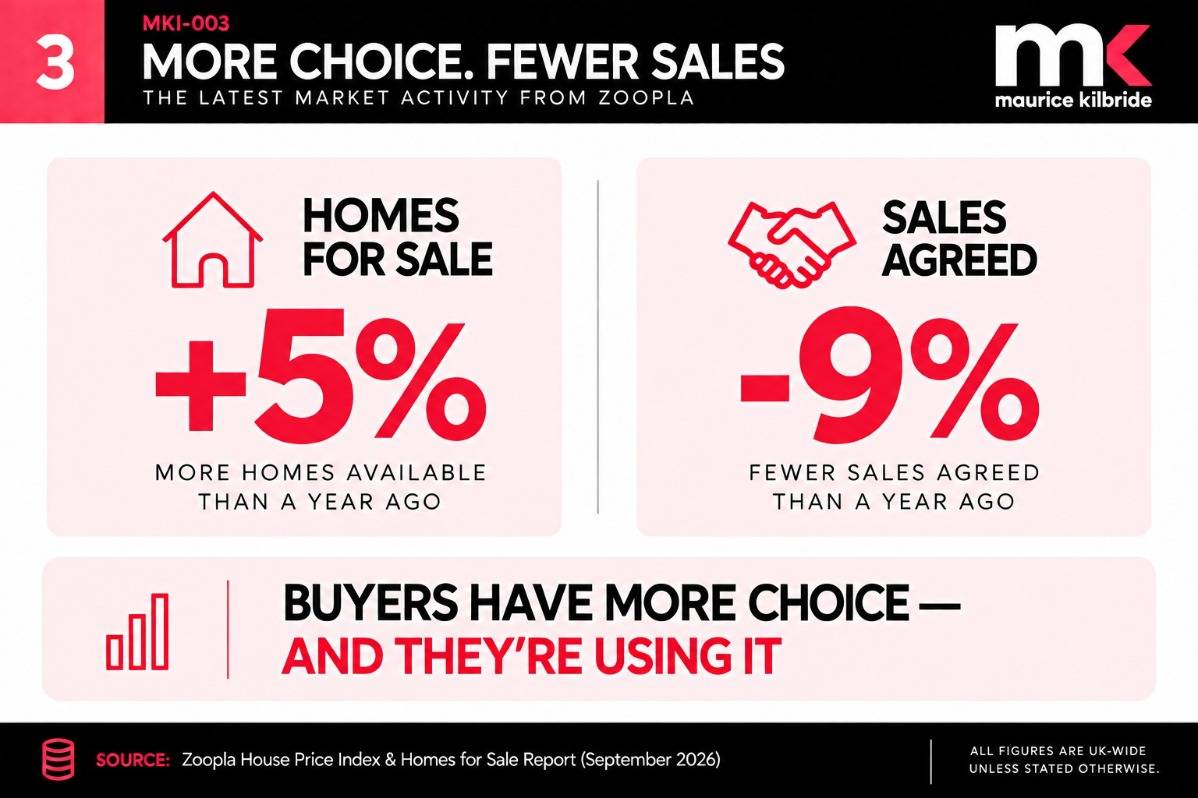
More choice. Fewer sales.
Perhaps October's most revealing statistic.
Zoopla reports more homes available for sale than a year ago, while fewer sales are being agreed.
Greater choice allows buyers to compare, negotiate and wait.
Getting attention is one thing. Converting it into a sale is another.
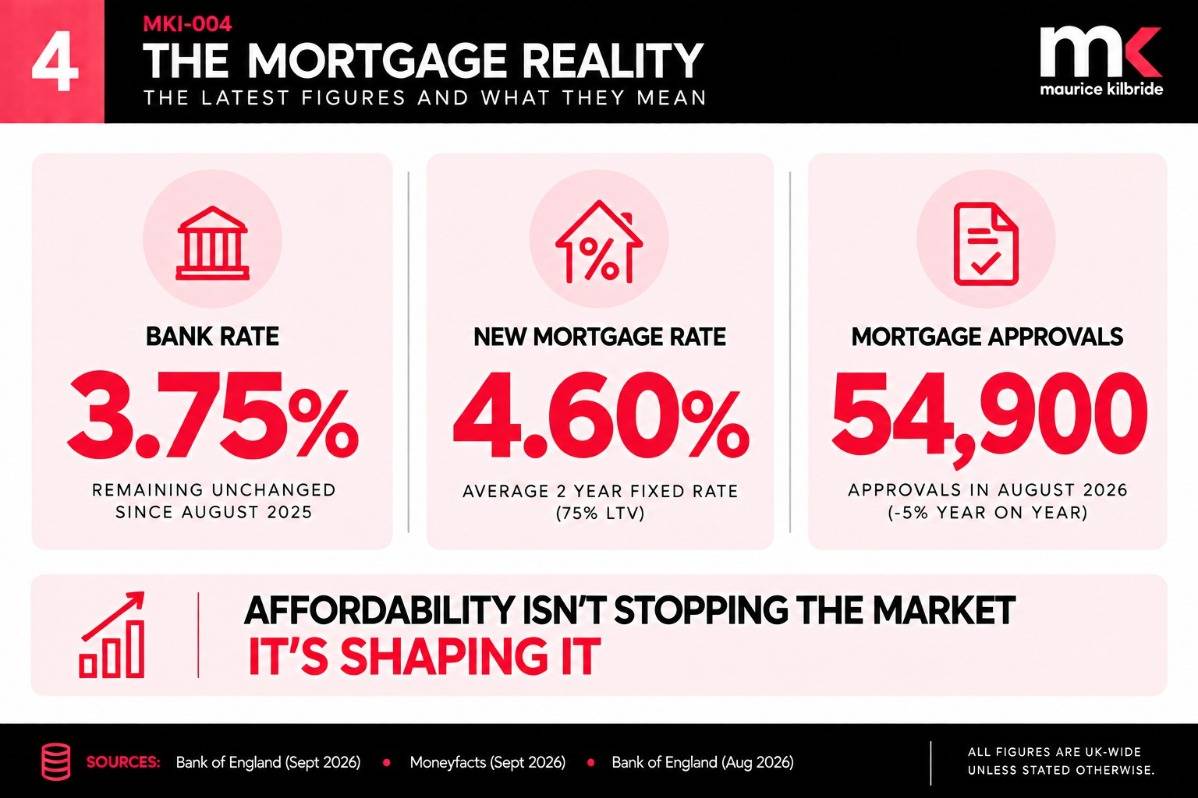
Affordability is shaping decisions
The effective rate paid on newly drawn mortgages increased to 4.60% in August, while mortgage approvals for house purchases slipped to 54,900.
That affects budgets, compromises and ultimately what buyers are prepared to pay.
Affordability isn't stopping the market. It's shaping it.
National figures provide the context. But property markets are ultimately local. So what happens when we bring the numbers home to Cheadle?
Cheadle is bucking the trend. But will it last?
Nationally, buyers have more choice and fewer sales are being agreed.
September's Cheadle figures tell a rather different story.
.png)
Fewer homes are coming to market
September saw 158 new listings, compared with 182 a year ago — a fall of 13.2%.
Detached listings actually increased, while supply fell across every other property type. Most notably, just 66 semi-detached homes came to market compared with 85 last September.
On its own, that doesn't tell us whether the market is getting stronger.
The next figures do.
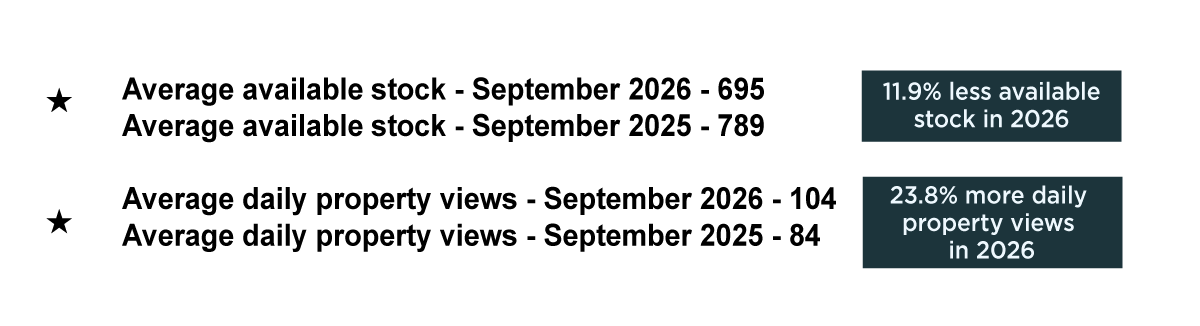
Less choice. More attention.
Available stock is 11.9% lower than a year ago, while average daily property views have increased 23.8%, from 84 to 104.
Fewer properties. Considerably more attention.
But is that interest actually turning into sales?
 And buyers are acting
It appears that it is.
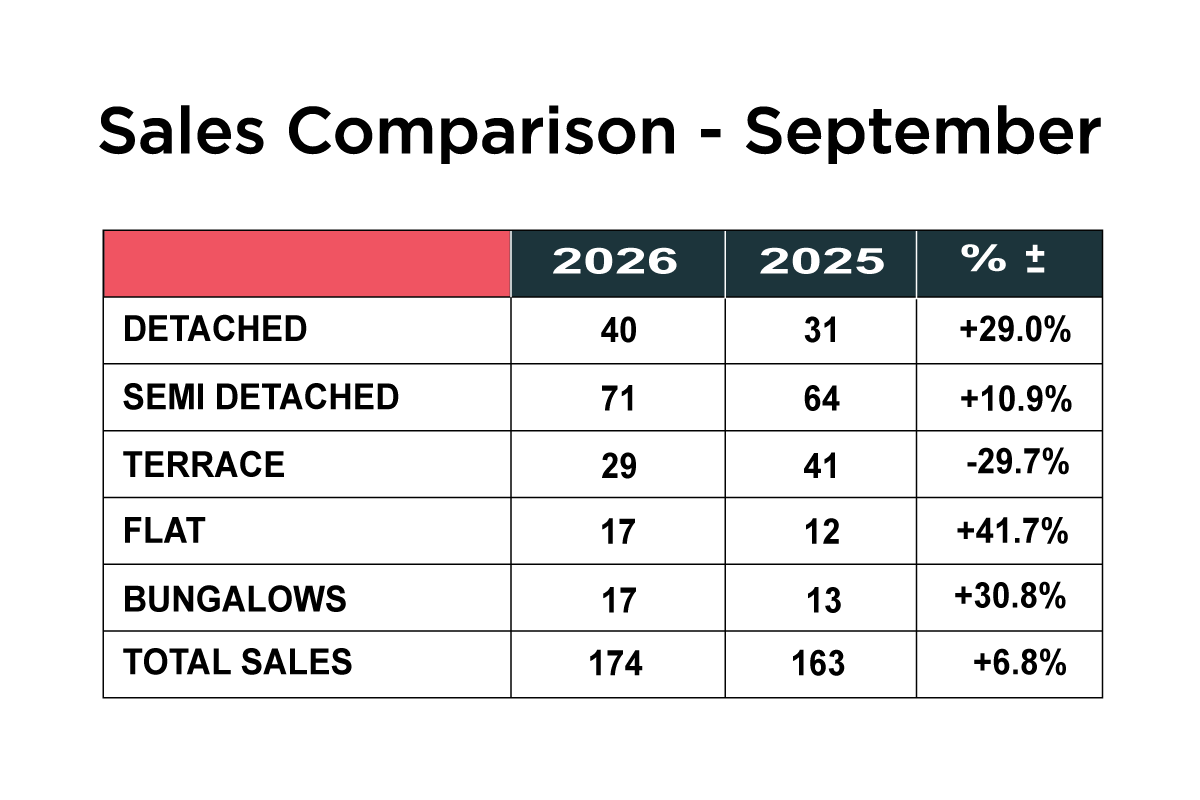
September recorded 174 sales compared with 163 last year — an increase of 6.8%.
Perhaps most interesting is the semi-detached market: new listings fell 25.2%, while sales increased 10.9%.
For such an important part of Cheadle's family market, that's worth watching.
 Where is the strength in SK8?
The strongest figures continue to come from traditional family homes.
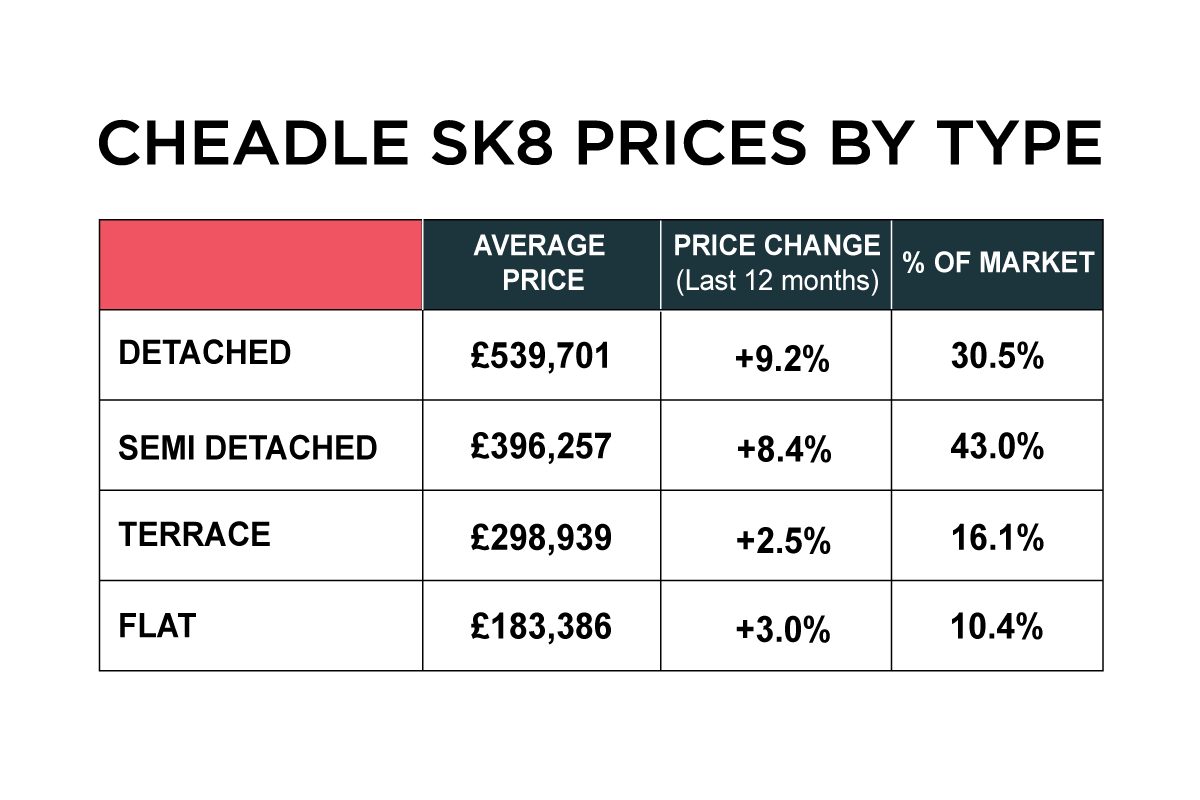
Detached and semi-detached properties account for almost three quarters of the SK8 market, with annual price movements of +9.2% and +8.4% respectively.
But these are averages, not evidence that every home has increased in value by 8% or 9%.
The figures suggest healthy demand for the right family property — not that buyers will pay any price for it.
 SK3 — a market of contrasts
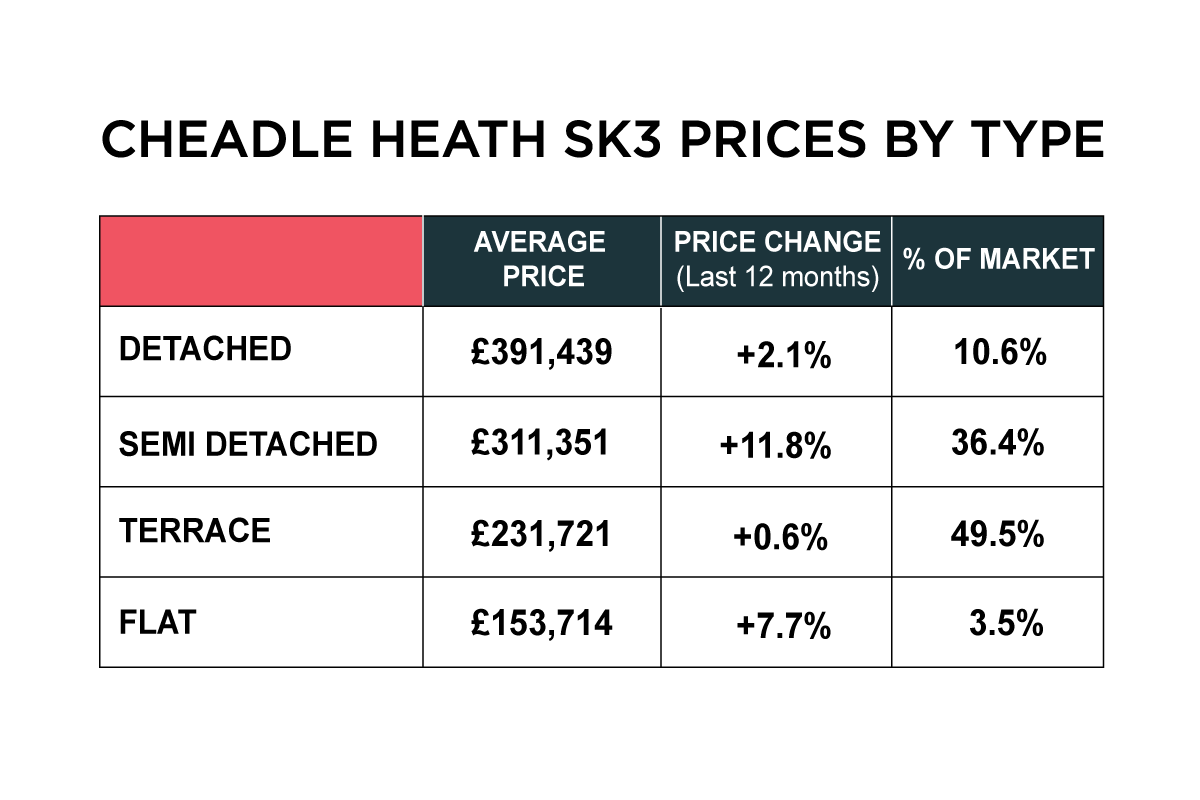
SK3 demonstrates why postcode averages need context.
Semi-detached homes recorded the strongest annual movement at +11.8%, while terraces, almost half the market, were broadly unchanged at +0.6%.
Different property types are moving at very different speeds.
The local rental market
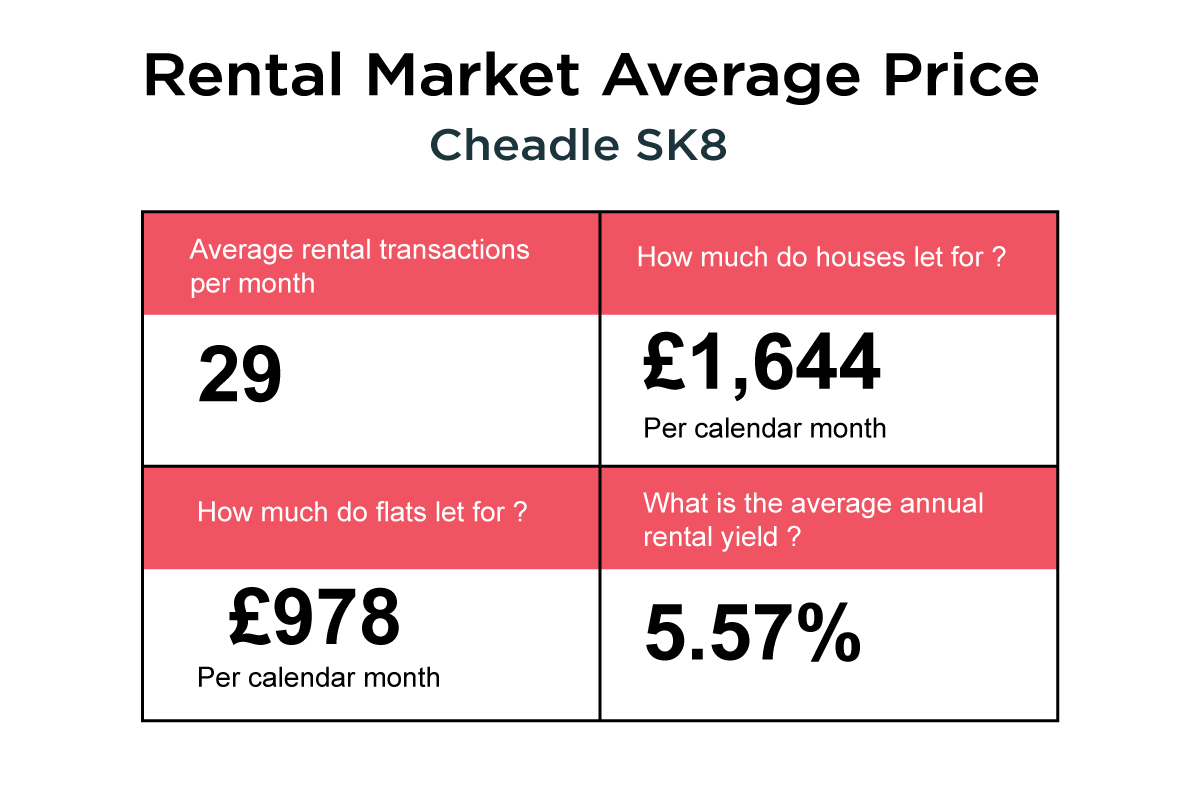
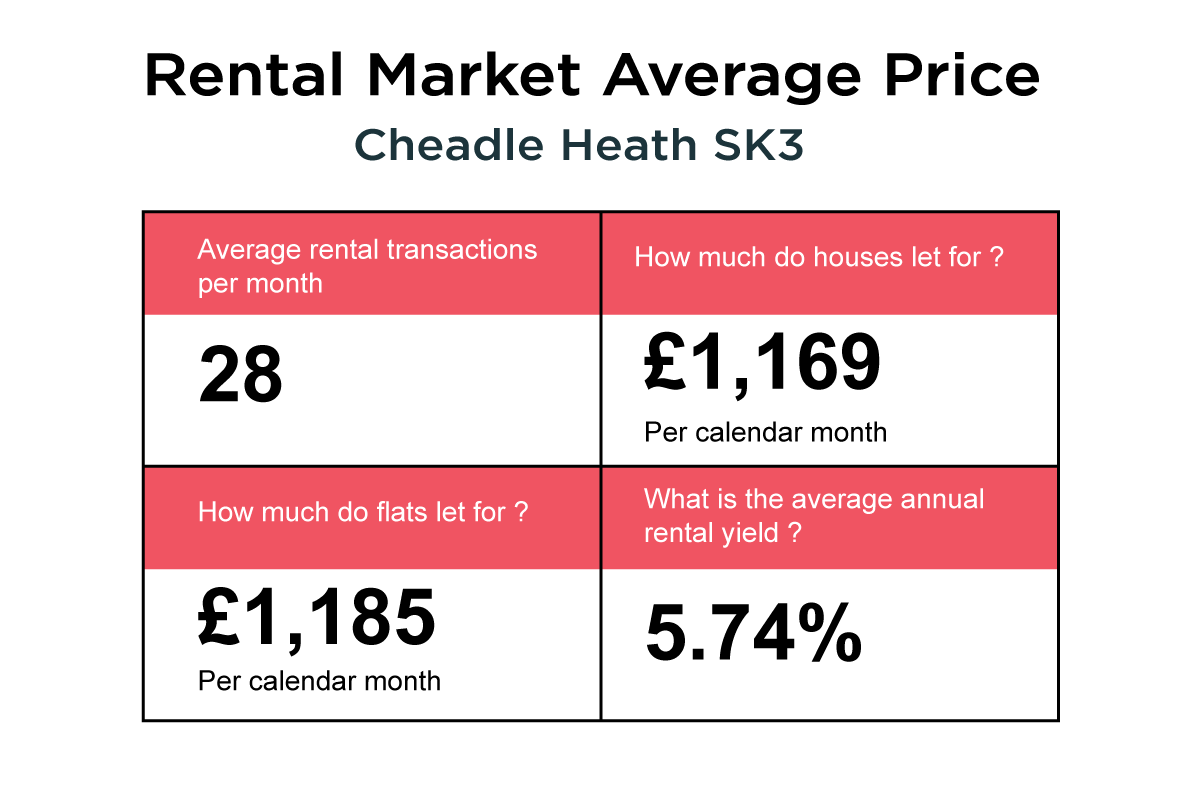
The rental figures continue to highlight the different characteristics of SK8 and SK3.
SK8 houses average £1,644 per month with an annual yield of 5.57%. In SK3, average house rents are lower at £1,169, but the headline yield is slightly stronger at 5.74%.
For landlords, the highest rent doesn't necessarily produce the highest return.
Maurice's Perspective
The buyer hasn't disappeared. The urgency has.
What interests me most this month is the contrast between the national picture and what we're seeing here in Cheadle.
Nationally, buyers have more choice and fewer sales are being agreed. Locally, September produced almost the opposite: fewer new listings, lower available stock, considerably more buyer attention and more sales.
I certainly wouldn't describe this as a return to a sellers' market. Buyers remain selective and affordability still matters.
But good homes are selling.
The buyer hasn't disappeared. The urgency has. That makes getting the price, presentation and launch right from day one more important than ever.
Whether September was simply a strong month or the beginning of something more sustained is what I'll be watching next.
Share this article
More Articles
Sign up for our newsletter
Subscribe to receive the latest property market information to your inbox, full of market knowledge and tips for your home.
You may unsubscribe at any time. See our Privacy Policy.

